UK Fintech Hiring Spikes Amid Compliance Push
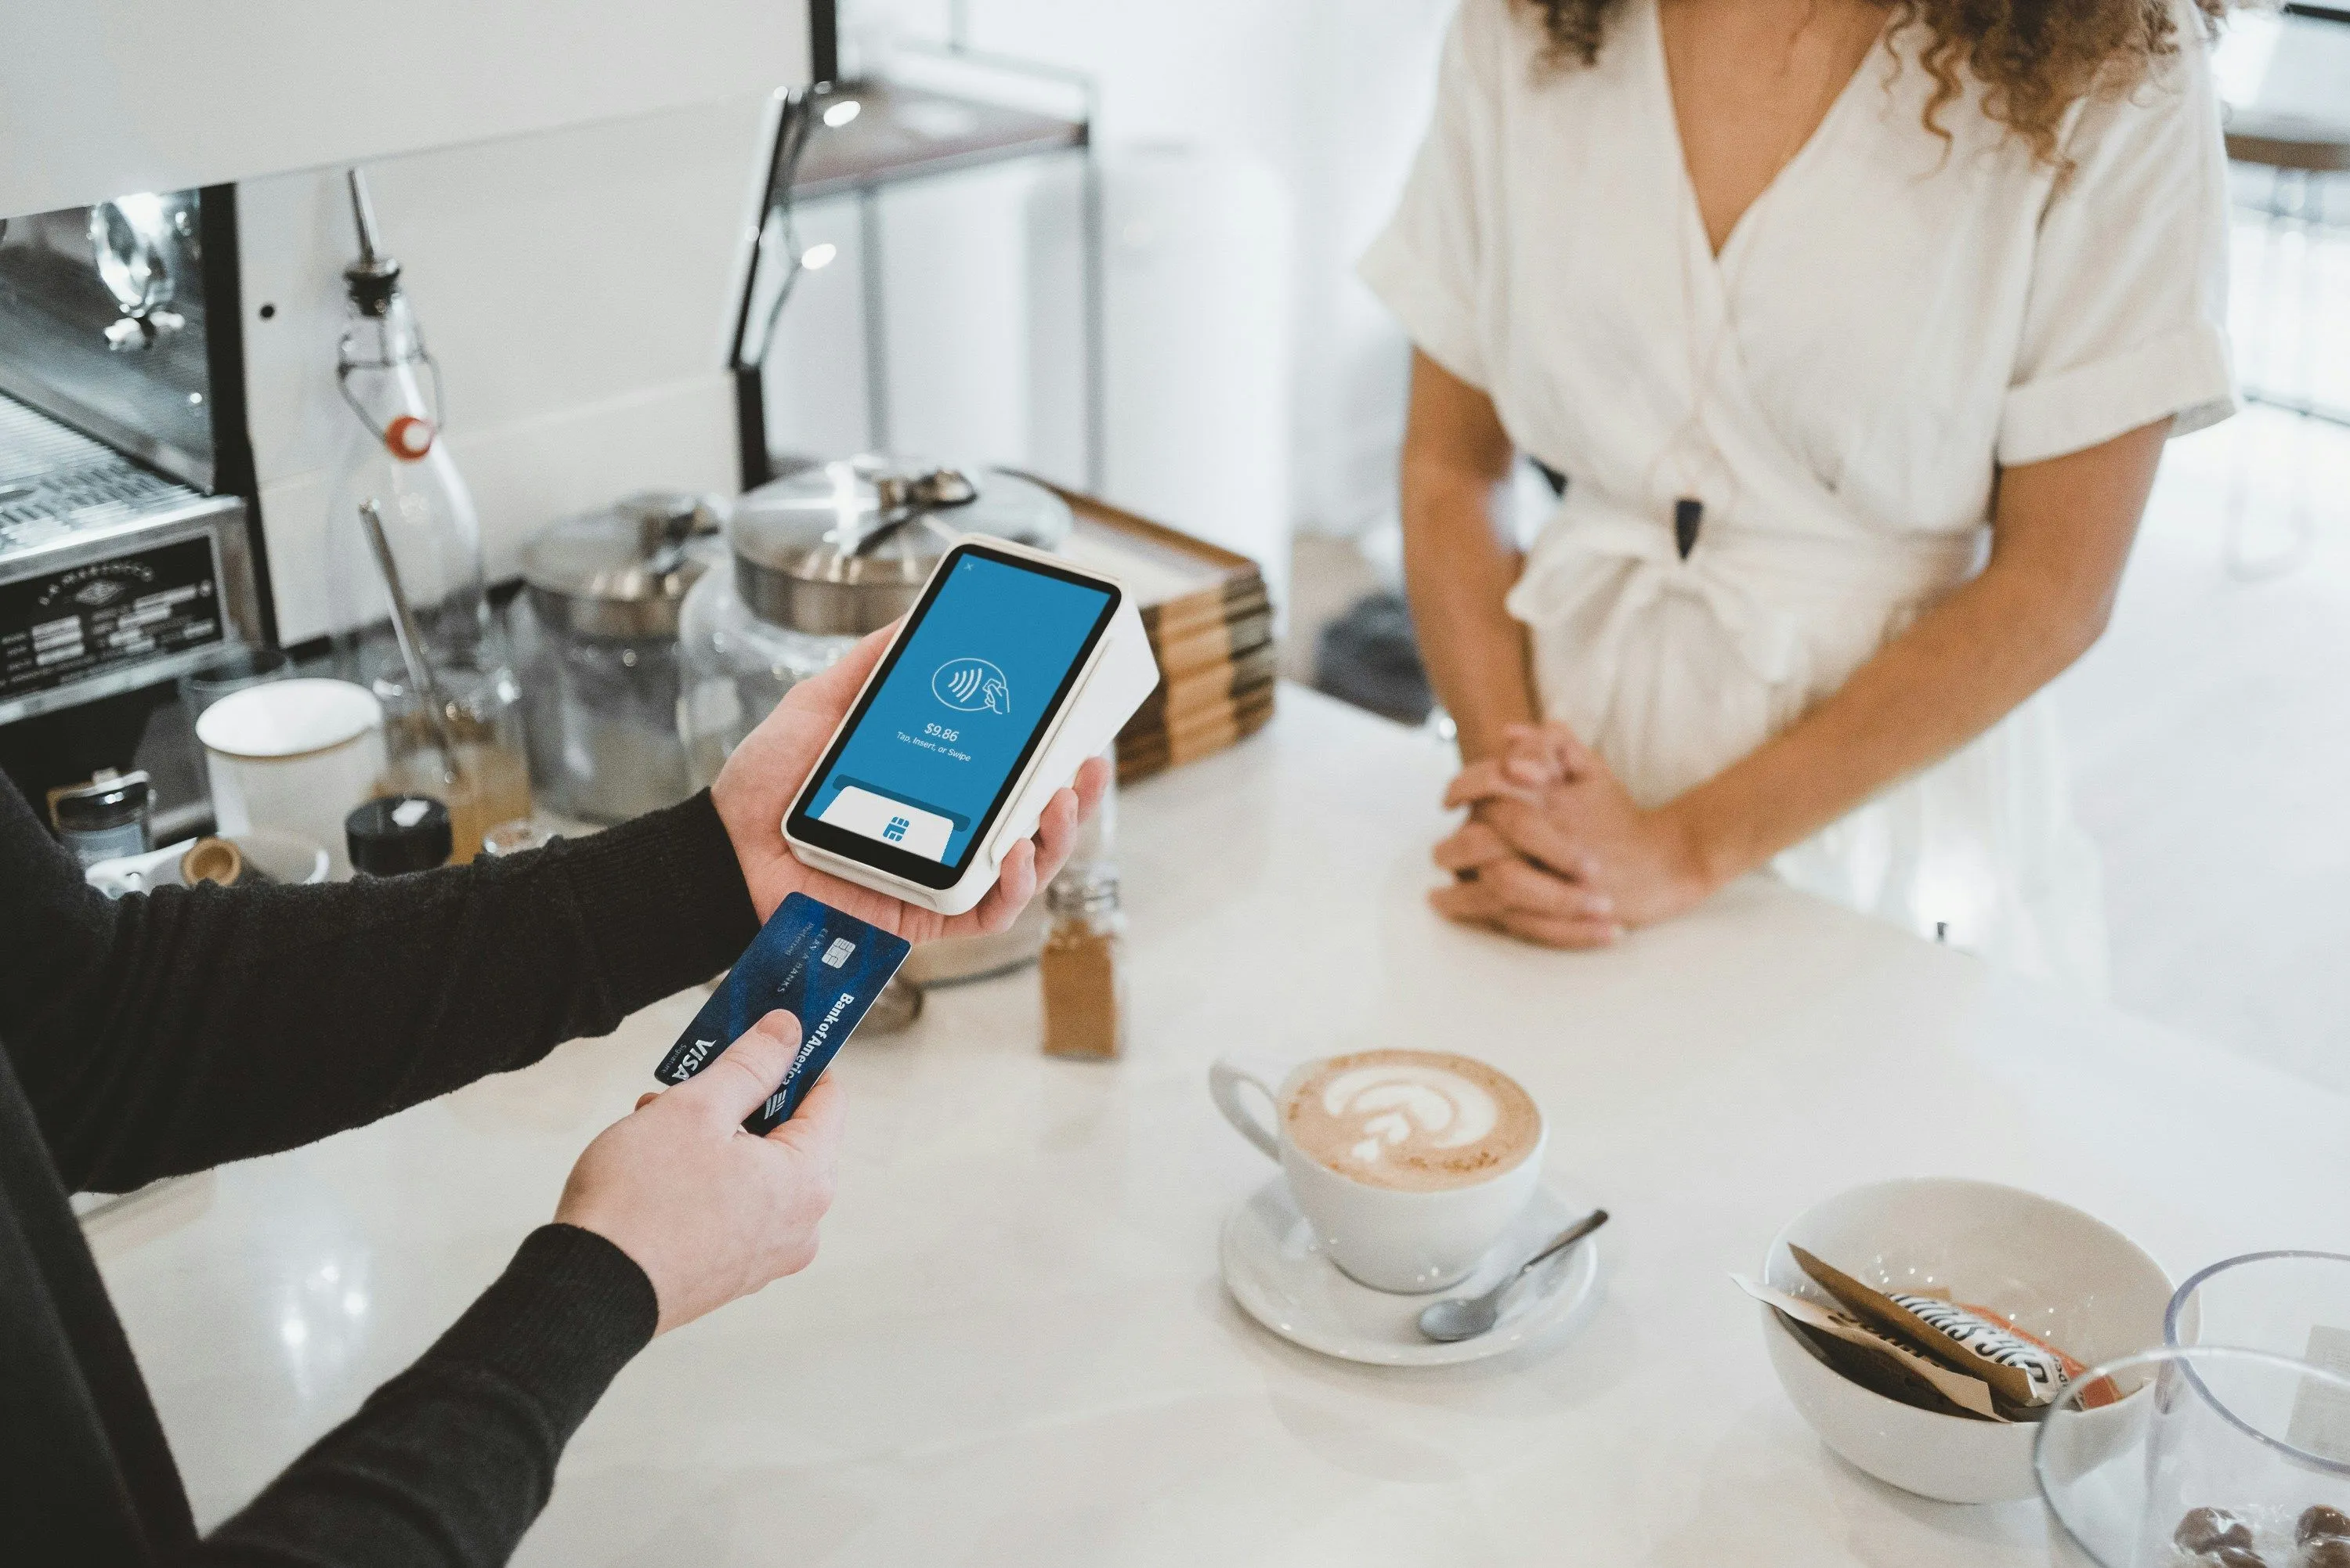
Behind the UK's fintech growth story is a quieter trend: compliance teams getting bigger. Here's why that matters, even if you're not the one doing the hiring.
While a lot of attention on the UK fintech sector focuses on funding rounds and new product launches, one of the more telling trends has been happening quietly in the background: compliance teams are growing faster than almost any other function in the industry.
It’s a direct response to increased regulatory scrutiny. The FCA has sharpened its focus on how payment and fintech firms handle everything from anti-money laundering checks to the Consumer Duty rules that came into force in 2023, which set a higher bar for how firms treat customers and communicate with them. Firms that once ran lean compliance functions are having to build them out properly — hiring specialists in financial crime, data protection, and regulatory reporting rather than treating compliance as a part-time responsibility bolted onto another role.
For fintech firms themselves, this is largely a cost of doing business in a sector that handles other people’s money — regulators expect scrutiny to scale with the risk involved, and payments is inherently a higher-risk activity than most. But the knock-on effect for the small businesses that rely on these firms is actually a positive one, even if it’s not always visible.
When a payments provider invests properly in compliance, it shows up downstream as fewer account freezes, faster and more transparent onboarding, and payment systems that are less likely to be exploited for fraud — all things a small business notices only when they go wrong. A provider with a thin compliance function is often the one where a merchant account gets suspended without warning, or a legitimate transaction gets flagged and delayed.
Pulsare Pay is built with this in mind: proper compliance and security aren’t treated as a back-office cost to minimise, but as part of what keeps a merchant’s payments running reliably — so business owners can focus on running their business, while we handle the regulatory side of keeping their payments safe.